What Does Your Business Need for GST Registration?
GST registration often gets delayed because the application describes the business premises incorrectly, uses a different legal name or includes documents that do not support the declared address. These problems can affect a home business, a rented shop, an online seller or a company operating from a shared office.
CBIC has now issued Circular No. 257/03/2026-GST dated 26 October 2026, explaining the documents applicants should submit and how officers should examine them. The guidance covers owned, rented, consent-based, inherited and co-working premises, along with verification, bank details and registration queries.
For business owners, the immediate task is to match the application with the actual business arrangement. A registered rent agreement, a parent’s property and a co-working membership require different supporting records.
This practical guide explains GST registration eligibility, updated documents, application steps, fees and timelines. It also separates current requirements from notified changes taking effect in November and December 2026.
What Is GST Registration and Why Is It Important?
GST registration identifies your business as a registered taxpayer through a 15-character GSTIN. A regular taxpayer can collect GST on taxable supplies and claim eligible input tax credit, subject to the applicable conditions.
The GSTIN format and verification process help you check whether the certificate reflects the correct taxpayer and State. Registration also creates continuing invoicing, recordkeeping and return filing responsibilities. Composition taxpayers follow different rules for collecting tax and claiming credit.
What Has Changed Under the October 2026 GST Registration Guidelines?
The CBIC circular dated 26 October 2026 gives applicants a detailed document checklist and directs officers to avoid unnecessary paperwork. Its six annexures include FAQs, business-wise and premises-wise checklists, and prescribed formats for an affidavit, undertaking and consent letter. Its main practical clarifications are:
-
A valid registered rent agreement can establish the business address without a separate utility bill being routinely demanded.
-
Property belonging to a parent, spouse, partner or director is not automatically the applicant entity’s own premises.
-
Co-working arrangements need documents identifying the allocated space and the provider’s right to use the property.
-
Bank details are optional when applying, but mandatory within the prescribed period after registration.
-
Officers should avoid objections based merely on residential premises, domestic electricity connections or the applicant living elsewhere.
-
Deficiencies must be raised through FORM GST REG-03 on the portal.
Applicants must still establish a genuine business location and provide complete, legible records.
Who Needs GST Registration in India?
Below are some occasions for which GST registration is needed:
Annual Turnover Limits
Registration generally becomes necessary when aggregate turnover exceeds the applicable threshold, subject to exemptions and compulsory registration provisions.
|
State or Union Territory |
Eligible exclusive goods suppliers |
Service or mixed suppliers |
|
Most States and Union Territories |
₹40 lakh |
₹20 lakh |
|
Arunachal Pradesh, Meghalaya, Sikkim, Uttarakhand, Puducherry and Telangana |
₹20 lakh |
₹20 lakh |
|
Manipur, Mizoram, Nagaland and Tripura |
₹10 lakh |
₹10 lakh |
The ₹40 lakh exemption is conditional. It excludes specified goods, including ice cream, pan masala, tobacco and notified bricks or tiles, and certain compulsory-registration cases. Being excluded from this higher exemption does not, by itself, mean every such supplier must register from the first sale; check the underlying threshold and compulsory-registration provisions. The State-wise limits above follow section 22 and the goods exemption in Notification No. 10/2019-Central Tax, read with its amendments.
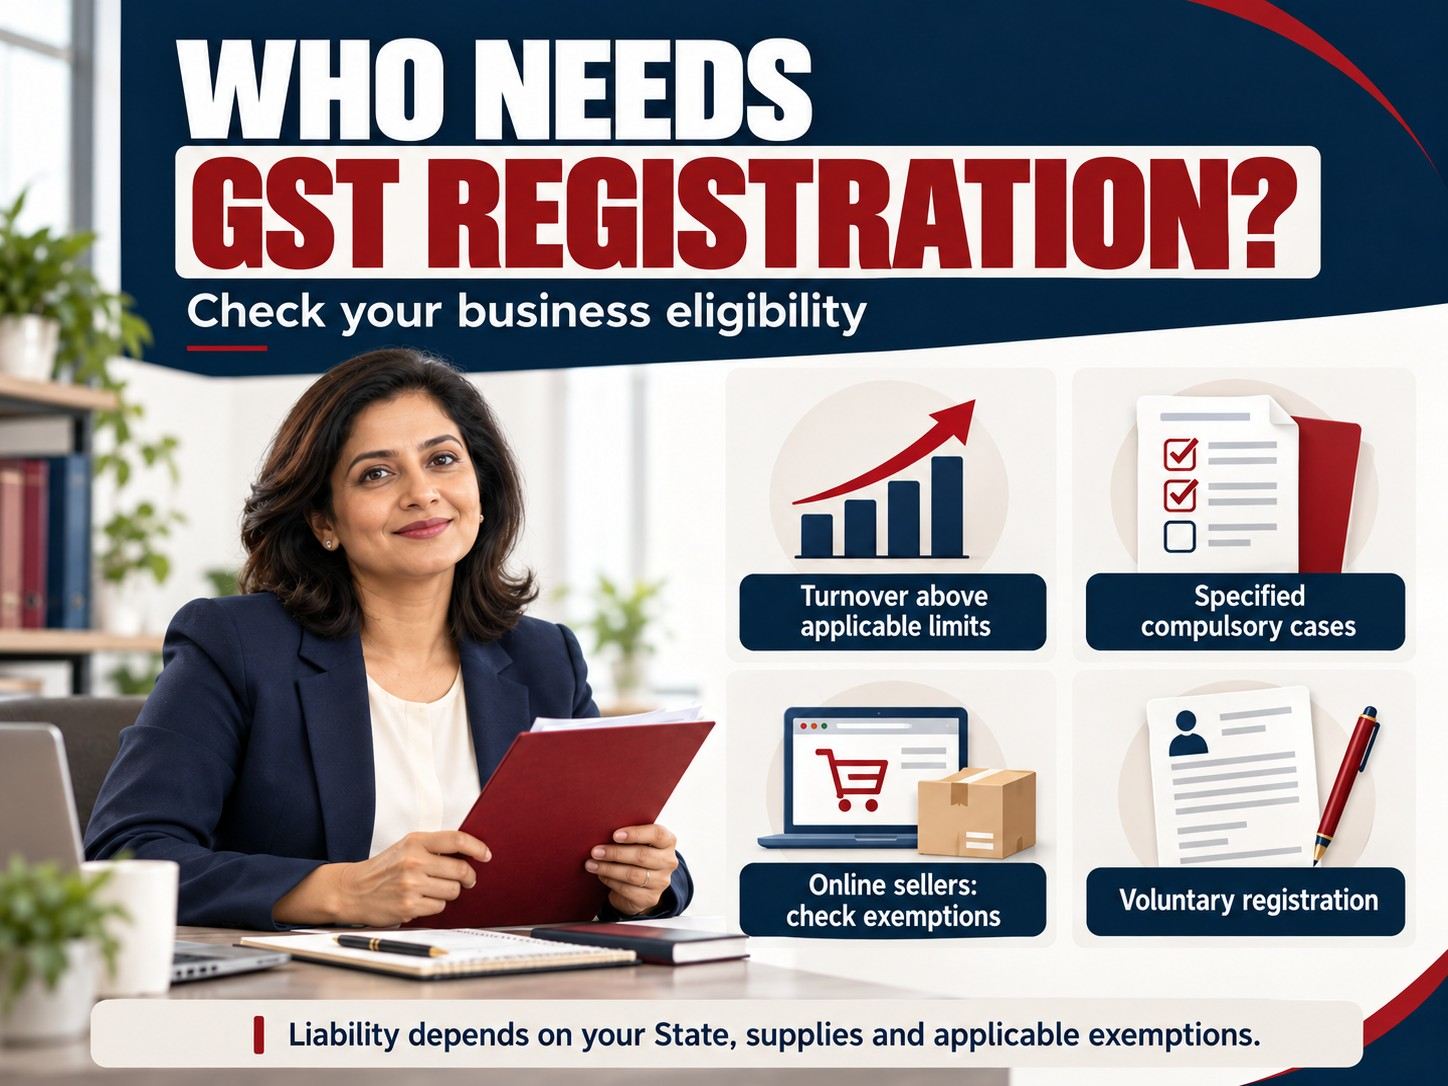
Aggregate turnover is calculated across India under the same PAN. It includes taxable supplies, exempt supplies, exports and interstate outward supplies. GST and inward supplies taxable under reverse charge are excluded.
Compulsory Registration and Exemptions
Compulsory registration can apply to interstate taxable goods suppliers, casual and non-resident taxable persons, specified agents, Input Service Distributors and persons liable under notified reverse charge provisions, among others.
However, eligible interstate service suppliers can remain exempt below the applicable ₹20 lakh or ₹10 lakh limit. Exclusive suppliers of wholly exempt or non-taxable supplies may also be exempt. Ordinarily, a person becoming liable must apply within 30 days. Casual and non-resident taxable persons generally apply at least five days before starting business. An agriculturist is also exempt to the extent of supplies of produce from cultivation of land.
Online Sellers and Voluntary Registration
Eligible goods sellers through electronic commerce operators can use the conditional exemption under Notification No. 34/2023-Central Tax, effective from 1 October 2023. Requirements include turnover within the applicable limit in both relevant financial years, no interstate goods supplies, operation through operators in only one State or Union Territory, PAN and prescribed portal enrolment.
Voluntary registration is available below the threshold, but brings the applicable compliance responsibilities.
Which GST Registration Category Should You Choose?
The correct category depends on your activity and eligibility. State-wise registrations are a location requirement, rather than a separate taxpayer category.
|
Category or option |
When it applies |
|
Regular taxpayer |
Ordinary taxable supplies, with eligible input tax credit and normal invoicing and return obligations |
|
Composition option |
Eligible small businesses choosing the prescribed turnover-based levy and its restrictions |
|
Casual taxable person |
Occasional taxable business in a State or Union Territory where the person has no fixed place of business |
|
Non-resident taxable person |
The statutory category for occasional taxable supplies by a person with no fixed place of business or residence in India |
|
Special categories |
ISD, GST TDS/TCS and specified overseas suppliers, using their applicable forms and procedures |
For eligible composition taxpayers under section 10(1), the preceding-year turnover ceiling is generally ₹1.5 crore, or ₹75 lakh in Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura and Uttarakhand. Eligible service or mixed suppliers under section 10(2A) have a ₹50 lakh ceiling. Activity restrictions also apply.
Composition taxpayers cannot collect GST separately, claim input tax credit or make interstate outward supplies. Rule 14A, explained below, simplifies registration; it is not the composition levy.
Which Documents Are Required for GST Registration?
The legal name, PAN and constitution must agree with the entity’s records. Choose the correct business category before uploading documents.
|
Business structure |
Main identity and constitution documents |
|
Proprietor’s PAN, personal details and recent photograph |
|
|
Firm’s PAN, partnership deed, partner details and photographs |
|
|
LLP’s PAN, incorporation proof, designated partner details and photographs |
|
|
Private limited company or other company |
Company’s PAN, incorporation certificate, relevant director details and authorised signatory documents |
|
HUF, trust, society or association |
Entity’s PAN, prescribed constitution proof and relevant Karta, trustee or committee details |
Every applicant also needs appropriate premises proof, business activity details, relevant HSN or SAC information and authorised signatory particulars. Upload the prescribed authorisation letter or resolution where applicable.
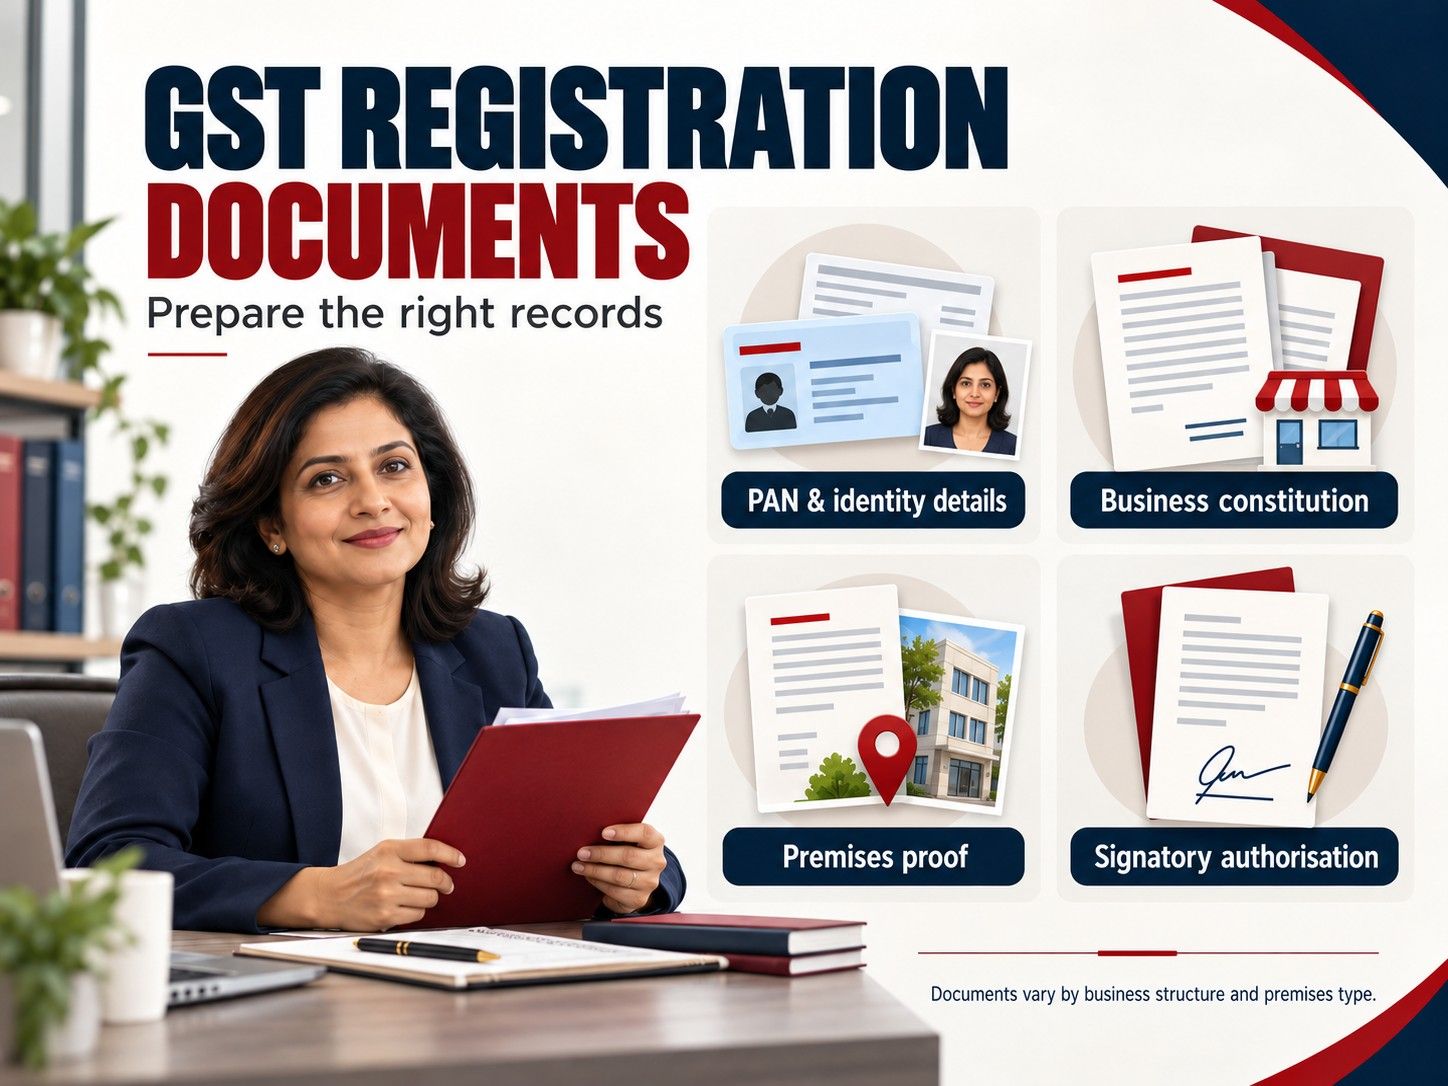
Provide correct DIN particulars for company directors and LLP designated partners where required. For government departments, PSUs and local or statutory authorities, use the specific constitution and authorisation records in Annexure II.
Use recent individual photographs. A cropped photograph from a PAN or Aadhaar card should not replace the required photograph. Companies and LLPs must follow the portal’s DSC requirement for signing.
Which Address Proof Is Accepted for GST Registration?
The principal place of business is the main location declared within the State of registration. Give the complete address, including the shop, flat, plot, cabin or desk identification where applicable.
Premises Owned by the Applicant
Upload one prescribed document in the applicant’s name showing the address. Accepted options include a latest property tax receipt, municipal khata, property identification document, latest electricity bill or latest water bill.
A director’s personal property does not become company-owned premises. Choose ownership, rent or consent according to the actual arrangement.
Rented Premises With an Agreement
If a valid registered rent or lease agreement is available, upload that agreement. Separate ownership evidence should not be routinely demanded in this situation.
Where registration of the agreement is not legally required, upload the unregistered agreement with one prescribed premises document in the landlord’s name. A latest electricity or water bill in the tenant applicant’s name may accompany the agreement instead of the lessor’s premises proof.
An unregistered agreement does not satisfy a separate legal requirement to register the lease.
Rented Premises Without an Agreement
Upload the undertaking prescribed in Annexure V of the circular, with evidence showing the tenant applicant’s possession. The circular gives a recent electricity or water bill in the tenant’s name, showing the full address, as an example.
The undertaking alone is insufficient.
Family Property and Consent-Based Premises
If a parent, spouse, partner, director or another owner permits use of the premises, provide the signed consent letter on plain paper in the Annexure VI format. Add one prescribed premises document in the owner’s name.
The consent letter must identify the parties, property and relationship. A non-owner relying on consent for jointly owned property needs all owners’ consent. An applicant who is themselves a joint owner need not obtain other co-owners’ NOCs, but must establish their own ownership.
Co-Working Spaces
For co-working space, upload the membership agreement identifying the period, address and allocated desk, cabin or suite. Add the provider’s prescribed ownership document, or its valid registered lease with the property owner, according to the arrangement.
Property in a Deceased Ancestor’s Name
Provide the death certificate, the Annexure IV affidavit explaining lawful inheritance and possession, and one prescribed premises document in the ancestor’s or applicant’s name. The affidavit format requires non-judicial stamp paper of at least ₹100 and execution before a First-Class Judicial Magistrate, Executive Magistrate or Notary Public.
SEZ Units and Developers
SEZ applicants must upload the valid approval or permission issued by the Development Commissioner. SEZ and non-SEZ establishments require separate registrations.
Additional Locations and State-Specific Details
Declare relevant additional business locations within the State and provide premises proof for each. The same documentary principles apply when amending a principal or additional place of business. Unmanned telecom towers and bank ATMs need not be declared as business locations.
The circular identifies electricity board and consumer-number fields for Maharashtra, Rajasthan, Odisha, Andhra Pradesh, Assam and Madhya Pradesh. Complete the State-specific fields shown on the portal accurately.
An Udyam registration certificate establishes MSME registration, but is not accepted as GST premises proof. A postal box or courier address also cannot replace a verifiable business location.
Unsure which premises category fits your business? Ask LegalBabu to review your GST documents.
Can You Use Simplified GST Registration Under Rule 14A?
Rule 14A is an optional route introduced from 1 November 2025 through Notification No. 18/2025-Central Tax. Eligible applicants declare that monthly output tax liability on supplies to registered persons, including applicable CGST, SGST/UTGST, IGST and compensation cess, will not exceed ₹2.5 lakh and complete the prescribed Aadhaar authentication.
The GST Rule 14A requirements include only one registration under that rule per PAN in a State or Union Territory. Eligible applications receive registration electronically within three working days, subject to completing the required process.
The ceiling concerns output tax on B2B supplies, rather than turnover or net tax after input credit. For example, ₹10 lakh of B2B taxable supplies at 18% produces ₹1.8 lakh output tax. A GST tax calculation tool helps calculate invoice tax, although eligibility requires checking the complete monthly position.
To leave the scheme, file FORM GST REG-32, clear due returns, and obtain approval before declaring supplies beyond the permitted limit. For withdrawal applications filed on or after 1 April 2026, returns for at least one tax period must have been furnished. All due returns must be filed, required particulars updated, and the applicable restrictions concerning pending amendments, cancellation applications or cancellation proceedings checked.
How to Apply for GST Registration Online?
Below is the process for applying for GST Registration:
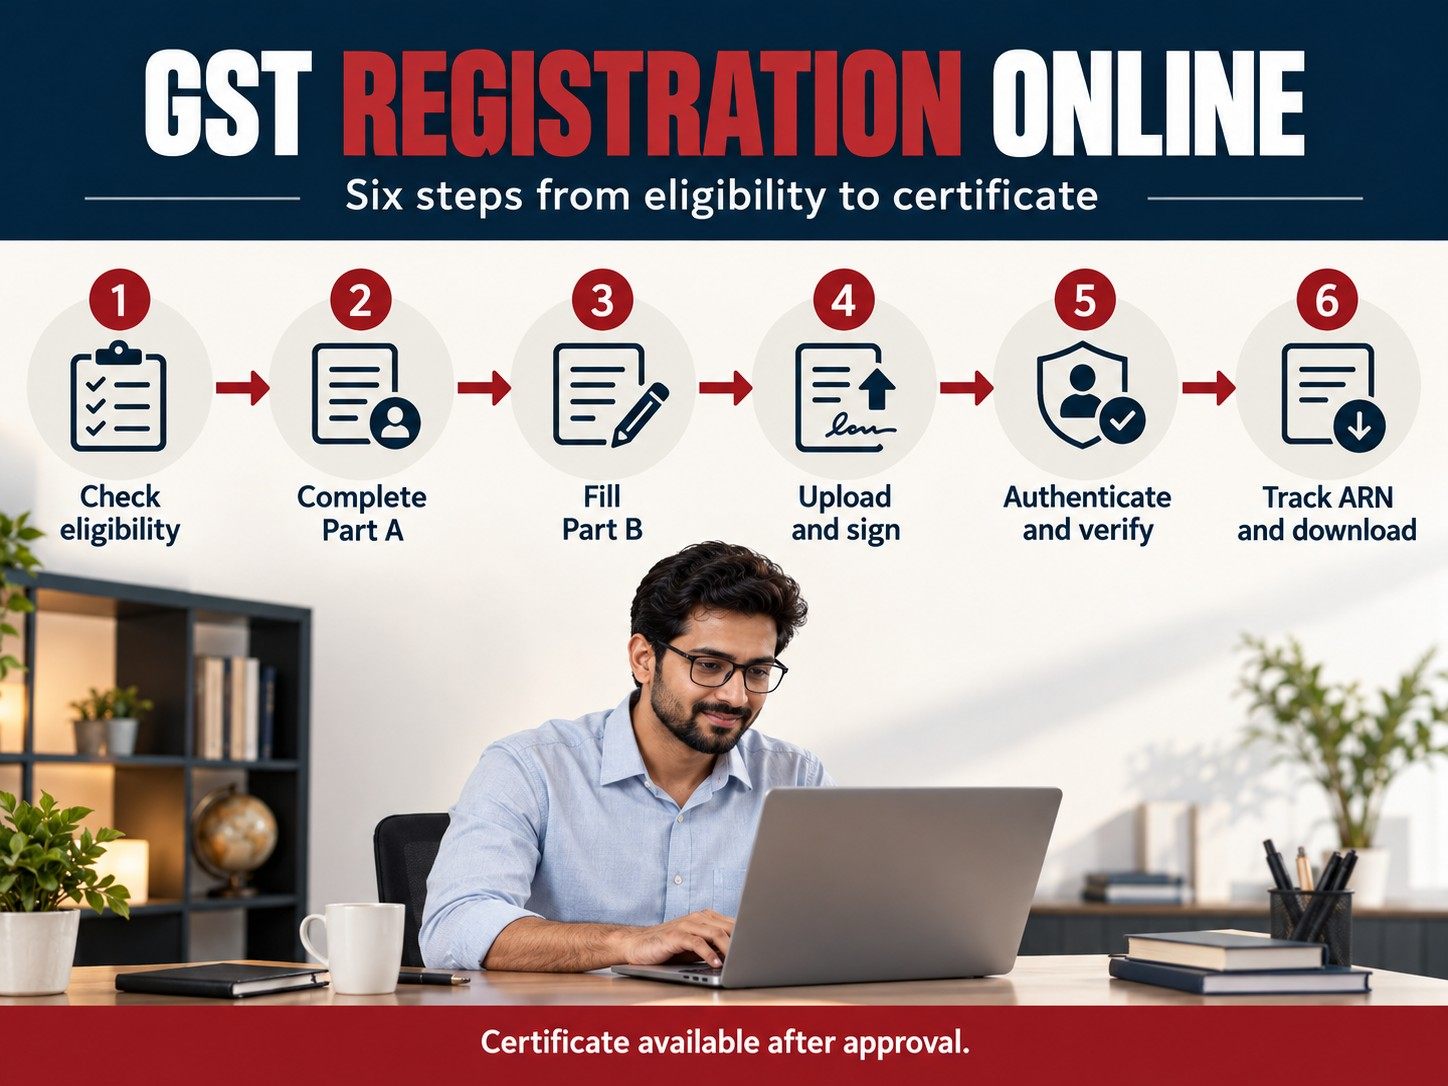
Step 1: Check the Registration Category
Confirm turnover, exemptions, State, business constitution and the appropriate taxpayer category. Check the composition option and Rule 14A separately. An ordinary domestic taxpayer applies in FORM GST REG-01; special categories have different forms.
Step 2: Complete Part A
Visit the official GST portal through Services → Registration → New Registration. Enter the correct PAN-linked legal name, State, district, mobile number and email address.
Step 3: Fill Part B Using the TRN
Use the Temporary Reference Number to enter constitution, promoters or partners, signatories, premises, activities and goods or services. A proprietor’s legal name follows their PAN, while the trade name is entered separately.
Step 4: Upload Documents and Sign
Check address consistency, agreement validity and document legibility. Submit using the signing method permitted for the entity, including DSC where mandatory.
Step 5: Complete Authentication and Verification
Follow the portal’s Aadhaar instructions. If selected for biometric authentication and original-document verification, attend the designated centre within the specified period. The circular identifies 15 days from receipt of the TRN.
Step 6: Track the ARN and Download the Certificate
Monitor the Application Reference Number and portal notices. After approval, download FORM GST REG-06 through Services → User Services → View/Download Certificates. Verify the GSTIN, legal and trade names, address and effective date.
What Mistakes Can Delay or Prevent GST Registration?
Before submitting, check for:
-
A trade name entered as the PAN-linked legal name.
-
A family member’s or director’s property incorrectly declared as applicant-owned.
-
An expired agreement or a missing desk, flat or shop number.
-
Unreadable uploads, incomplete pages or photographs cropped from identity cards.
-
Incomplete authorisation, Aadhaar or biometric verification.
-
Unresolved returns or liabilities from a previous department-cancelled registration under the same PAN.
Keep copies of the submitted application, supporting records and acknowledgements. Monitor the portal after filing so that a notice does not remain unanswered.
How Long Does GST Registration Take?
|
Application route |
Prescribed period |
|
Eligible Rule 14A or system-selected Rule 9A application |
Three working days, subject to applicable requirements |
|
Ordinary application with successful Aadhaar authentication and no physical verification requirement |
Seven working days from submission |
|
No/failed Aadhaar authentication or specified risk-based/officer-approved physical-verification case |
Thirty days from submission |
|
Applicant replying in FORM GST REG-04 |
Seven working days from receipt of REG-03 |
|
Officer deciding after the REG-04 reply |
Seven working days from receipt of the reply |
For physical-verification cases, the officer must upload FORM GST REG-30 with the prescribed report and supporting material at least five days before the 30-day period expires.
Authentication and verification affect application completeness. A query introduces a reply and decision stage, so approval cannot be promised within one fixed period for everyone. Deemed approval applies where no action is taken within the prescribed Rule 9 period.
Is a Bank Account Mandatory When Applying?
Bank details are optional at the application stage. Under Rule 10A, the relevant registered person must furnish them within 30 days of registration or before furnishing outward supply details in GSTR-1 or IFF, whichever is earlier.
The account must be in the registered person’s name and linked to the same PAN. Supporting evidence can include the relevant statement or passbook page, or a cancelled cheque containing the required details.
What Are the GST Registration Fees?
The government charges no application fee for GST registration. Professional assistance charges are separate and depend on the service agreed. Any expense for a DSC, affidavit, or legally required lease formalities is also separate from the government’s GST application fee.
Registration assistance and recurring compliance should be priced clearly. Maintaining business records through small business accounting services can also help prepare accurate tax filings after approval.
How Should You Respond to a GST Registration Query?
Read FORM GST REG-03 and reply through FORM GST REG-04 within seven working days. Address every deficiency and provide the relevant legible document. Understanding the GST notice reply process helps keep the response tied to the notice and its deadline.
The circular limits deficiency queries to genuine issues such as incomplete or unreadable records, mismatched or inadequate address proof, or an incomplete address. Officers should not raise presumptive objections about the applicant living in another State, a domestic electricity connection or residential premises. Other laws governing property use still apply.
For undue delay or unwarranted queries, the circular permits a grievance to the jurisdictional Chief Commissioner of Central Tax or Commissioner of State Tax through the special email identified by the relevant Zone or State.
Which Notified Registration Changes Take Effect After 29 October 2026?
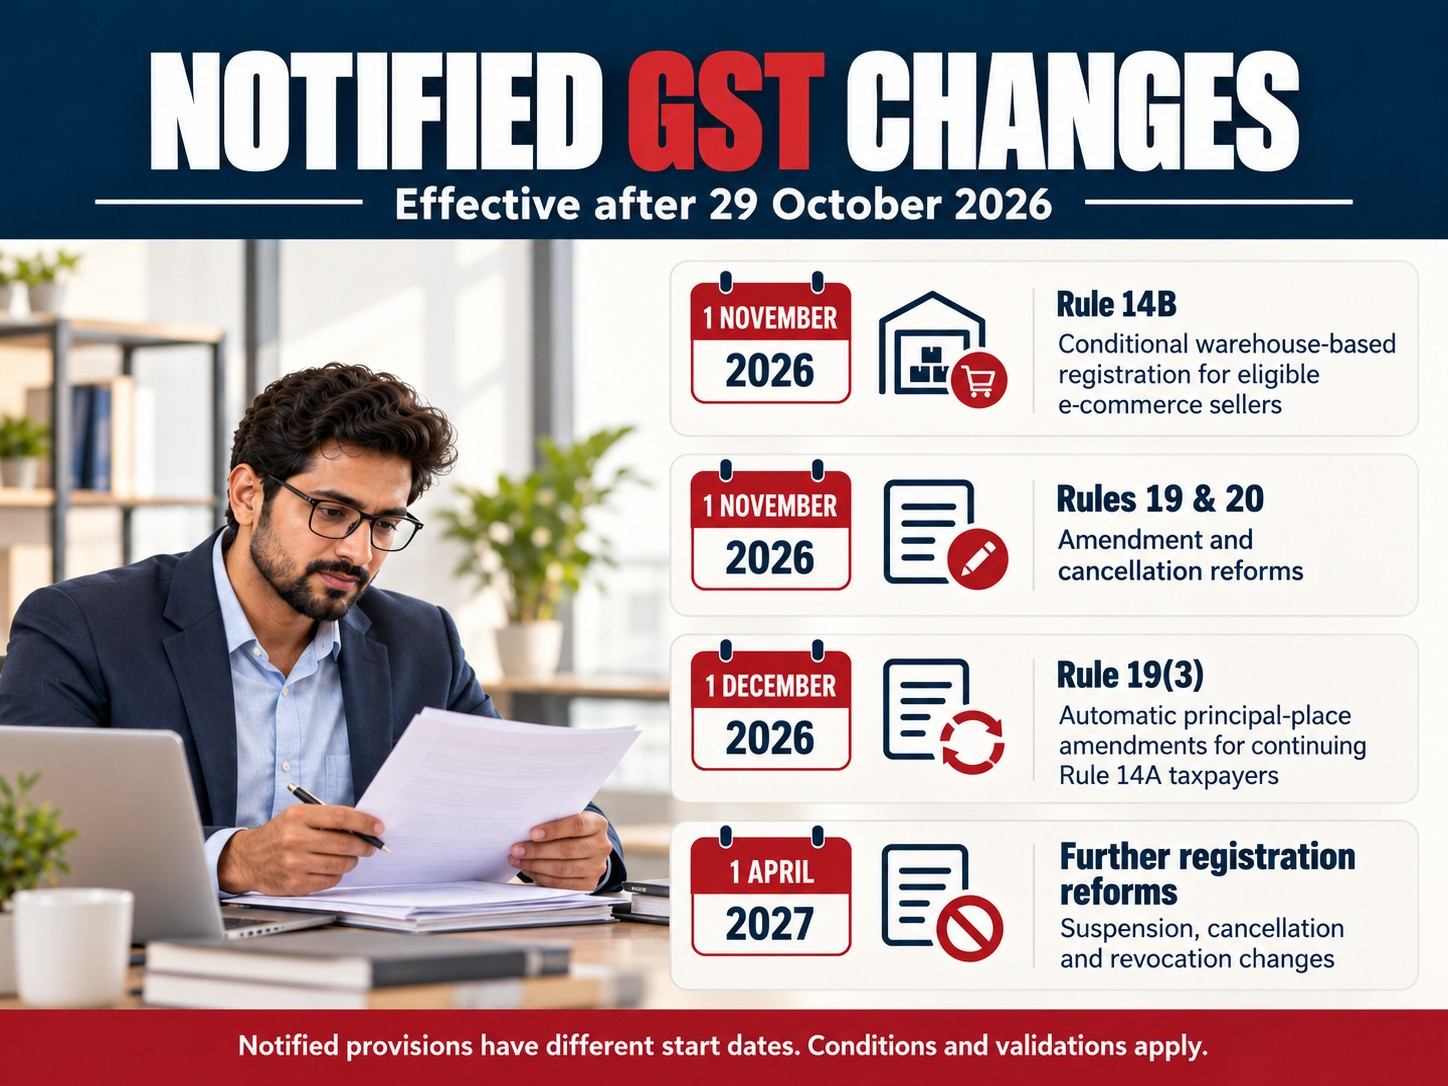
Notification No. 05/2026-Central Tax dated 26 October 2026, published in the Gazette of India, introduces changes after this article’s update date. As of 29 October 2026, these provisions are notified but have not yet taken effect.
|
Effective date |
Change |
|
1 November 2026 |
Rule 14B introduces conditional registration for eligible goods sellers through electronic commerce operators in other States, using an operator’s warehouse as the business address. |
|
1 November 2026 |
Revised Rule 19 provides automatic processing of particulars other than principal place of business details, subject to validations. |
|
1 November 2026 |
Revised Rule 20 introduces conditional system-based cancellation on the taxpayer’s request; return filing and payment conditions apply. |
|
1 December 2026 |
Revised Rule 19(3) provides automatic principal-place amendment for taxpayers continuing under Rule 14A, subject to validations. |
Rule 14B requires an eligible home-State registration, operator consent, required authentication and verification, and the prescribed ₹2.5 lakh monthly output tax ceiling on supplies to registered persons other than those under the same PAN. Home-State Rule 14A registrants must apply to withdraw before applying under Rule 14B. Separate State registration requirements remain. A change of business constitution that changes PAN still requires fresh registration. Further notified suspension, cancellation and revocation changes commence on 1 April 2027 and should not be applied early.
What Must You Do After Getting a GSTIN?
Display the certificate and GSTIN as prescribed, issue appropriate invoices or bills of supply, keep records and complete GST return filing requirements. Nil returns may remain necessary when there are no transactions.
Keep registered particulars current through the GST registration amendment process when the address, signatory or other details change. Regular registration normally continues until cancelled and needs no annual renewal.
If the business closes or ceases to be liable, follow the GST registration cancellation process and complete outstanding obligations. Exporters planning eligible supplies without IGST payment should separately check the GST LUT filing requirements.
What Is the Penalty for Not Obtaining GST Registration?
Failure to register when legally liable is an offence under section 122(1)(xi) of the CGST Act. Section 122(1) provides a penalty of ₹10,000 or the applicable tax-linked amount, whichever is higher. Corresponding State/UT GST consequences may also apply, along with tax and interest where due.
The final liability depends on the facts and applicable proceedings. Obtaining registration later does not clear earlier unpaid tax. A uniform 10% penalty does not describe every failure-to-register case.
Conclusion
GST registration starts with checking liability and choosing the correct applicant category. The latest circular makes accurate premises declarations and the prescribed supporting records particularly important.
LegalBabu can review your business details, prepare the relevant document checklist and assist with the application and departmental queries. Confirm the applicable registration route before submission and plan the compliance work that follows approval.
FAQS
FAQs About GST Registration
we have you covered:
-
Can I Apply for GST Registration at My Home Address?
Yes, where it is the genuine business location, and you provide the prescribed ownership, rent or consent documents. The premises must have a verifiable physical address. Officers should avoid subjective objections merely because it is residential.
- Can I Use My Parent’s Property Without a Rent Agreement?
- Is an Electricity Bill Compulsory With Every Registered Rent Agreement?
- Is a Commercial Electricity Connection Required?
- Can I Register Before Opening a Business Bank Account?
- Does Every Online Seller Need a GSTIN?
- Does Every GST Application Get Approved Within Three Days?
- Is the Rule 14A Limit Based on Turnover?
- What If I Miss a Registration Query Deadline?
- Can I Obtain Fresh Registration After an Earlier GSTIN Was Cancelled?
- Is GST Registration Required in Every State Where I Have Customers?


